Almost every Singaporean has heard of CPF LIFE long before turning 55. Far fewer know what it actually pays, or when. So what is it?
CPF LIFE (Lifelong Income For the Elderly) is Singapore's national annuity scheme. It turns the savings in your CPF Retirement Account into a monthly payout from age 65 for as long as you live. How much you receive depends on your Retirement Account savings, the plan you choose, when you start and life expectancy. Because women live longer on average, men receive higher monthly payouts on the same balance.
In a nutshell:
- At 55, your Retirement Account is formed. For members turning 55 in 2026, the Full Retirement Sum is S$220,400.
- From 65 (or as late as 70), it pays you every month for life. At the Full Retirement Sum, CPF Board estimates about S$1,780 a month on the Standard Plan.
- There are three plans: Standard (steady payouts), Escalating (payouts rise 2% a year) and Basic (lower payouts, a legacy plan).
What is CPF LIFE and why does it exist?
CPF LIFE is an annuity: a pool of savings that pays you a fixed income each month for the rest of your life. It was introduced in 2009 to solve one problem. Singaporeans are living longer, and a lump sum can run out while its owner is still alive.
It works by risk pooling, like insurance. Your CPF LIFE premium funds your monthly payouts, while the interest earned on members' premiums is pooled to keep everyone's payouts going for life. If a member passes away before their premium is used up, the remaining premium and any other CPF savings go to their beneficiaries. The interest earned on the premium is not refunded, because it belongs to the pool.
How does CPF LIFE work?
CPF LIFE happens in three stages: at 55, between 55 and 65, and from 65.
- At 55, your Retirement Account (RA) is created. Savings from your Special Account and Ordinary Account move into it, up to your Full Retirement Sum. Since January 2025, the Special Account closes at 55.
- From 55 to 65, the RA earns interest. The RA earns at least 4% a year, a floor the Government has extended to 31 December 2027. Members aged 55 and above also earn an extra 2% on the first S$30,000 of their combined CPF balances and an extra 1% on the next S$30,000, so part of the RA can earn up to 6%.
- From 65, payouts start. The payout eligibility age is 65, and you can choose to start any time up to 70. If you have not chosen by 70, payouts start automatically.
How much does CPF LIFE pay?
It depends mainly on how much is in your RA: the more you set aside, the higher the payout, up to the Enhanced Retirement Sum, the most CPF allows. CPF Board's estimates at its three retirement sums, the Basic (BRS), Full (FRS) and Enhanced (ERS) Retirement Sums, are:
| Retirement sum (turning 55 in 2026) | Amount | Estimated payout from 65* |
|---|---|---|
| Basic Retirement Sum (BRS) | S$110,200 | S$950 a month |
| Full Retirement Sum (FRS) | S$220,400 | S$1,780 a month |
| Enhanced Retirement Sum (ERS) | S$440,800 | S$3,440 a month |
*CPF Board estimates for a male member turning 55 in 2026, on the Standard Plan. CPF Board does not publish separate figures for women, whose payouts are slightly lower on the same balance because they live longer on average. CPF's payout estimator shows each member's own figure. Source: CPF Board, September 2026.
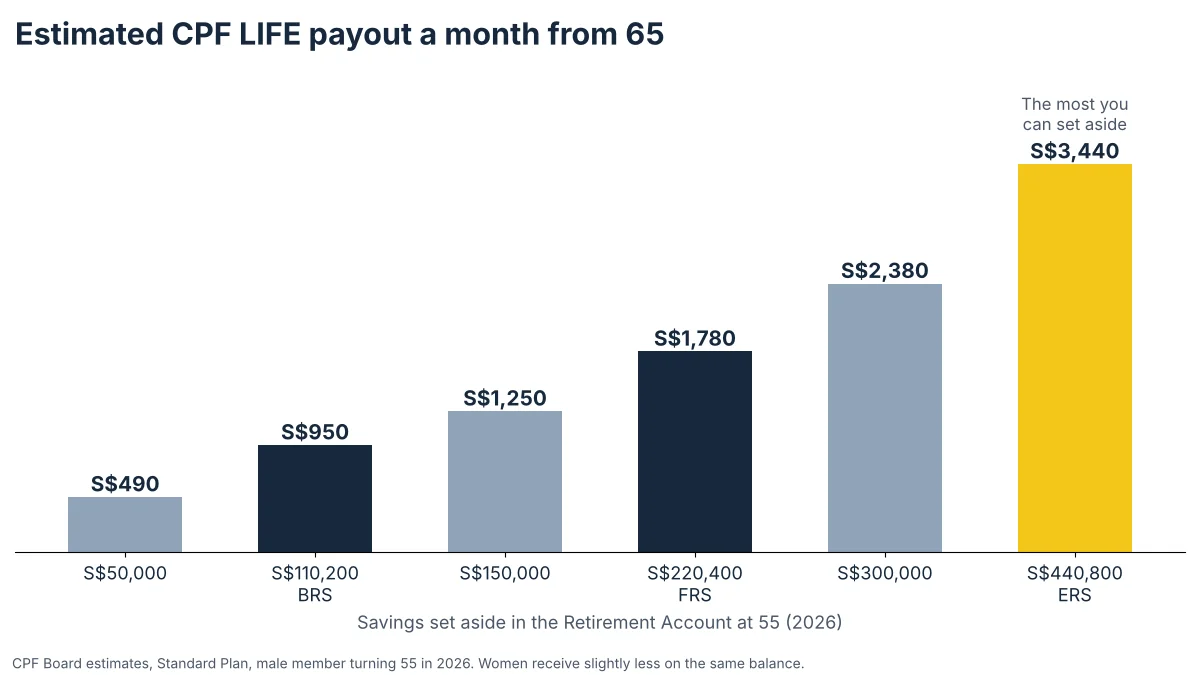
Payouts rise with every dollar set aside, not only at the three sums: about S$1,250 a month for S$150,000 and S$2,380 for S$300,000, up to S$3,440 at the ERS.
Which CPF LIFE plan should you choose?
The choice comes down to whether you want the highest payout now, payouts that keep up with prices, or more left for your family.
| Plan | How payouts work | Suits someone who |
|---|---|---|
| Standard Plan | Level payouts for life. All RA savings become the CPF LIFE premium. | Wants the highest steady payout and can trim spending as prices rise |
| Escalating Plan | Starts lower, then rises 2% every year for life | Worries about rising costs over a long retirement |
| Basic Plan | Only 10 to 20% of RA savings become the premium. Payouts come from the RA until 90 and get progressively lower. | Wants to keep more savings in the RA for beneficiaries, and accepts lower payouts |
CPF Board describes the Basic Plan as a legacy plan from 2009, and says most members will find the Standard or Escalating Plan more suitable.
How much CPF can you withdraw at 55 and 65?
At 55, members who have set aside the Full Retirement Sum (FRS) can take out everything above it, and property owners who pledge their home can take out Retirement Account savings above the Basic Retirement Sum. Everyone else can still take out up to S$5,000 of their Ordinary and Special Account savings, or the whole amount if it is less.
From 65, members born in 1958 or later can also take out up to 20% of their RA savings as a lump sum (top-ups and government grants are not counted). This 20% is an overall limit that includes the S$5,000 from 55. For example, with S$300,000 in the RA at 65, the limit is S$60,000: someone who took S$5,000 at 55 can take another S$55,000, and someone who took nothing can take the full S$60,000.
All of these withdrawals are optional, and smaller amounts can be taken. CPF balances at 55 vary widely, for example after years of self-employment, part-time work or time out of the workforce, so the CPF Retirement dashboard shows what each member can actually withdraw. Every dollar withdrawn lowers the monthly payout, so it is worth checking the trade-off in CPF's payout estimator first.
How can you increase your CPF LIFE payouts?
There are three common ways.
- Top up your account. Before 55, cash top-ups go into the Special Account. From 55, you can top up your RA to the current ERS. Cash top-ups also lower your taxable income, by up to S$8,000 a year for top-ups to your own account (a limit shared with MediSave top-ups) and up to another S$8,000 for top-ups to loved ones. This cuts the income that is taxed, not the tax bill itself. The tax saved is the top-up times your top tax rate, so it differs from person to person: an S$8,000 top-up saves about S$560 at the 7% rate (chargeable income of S$40,001 to S$80,000) and about S$1,200 at 15% (S$120,001 to S$160,000). Only top-ups up to the current year's Full Retirement Sum count.
- Start payouts later. Each year you defer from 65 adds up to 7% to your monthly payout, or up to 35% by 70. CPF Board's own example: a 55-year-old man with S$220,400 in his RA on the Standard Plan receives about S$600 more a month by starting at 70 instead of 65 (CPF Board).
- Leave savings in instead of withdrawing. Withdrawals at 55 and 65 are optional. Money left in CPF keeps earning interest and raises the payout.
Top-ups to the Special Account and RA are irreversible, so only money not needed before retirement belongs there.
Is CPF LIFE enough to retire on?
For some retirees, it can cover basic expenses. For the lifestyle many people picture, it is unlikely to be enough on its own.
At the Full Retirement Sum, the estimated payout is about S$1,780 a month from 65. Whether that is enough depends on housing, healthcare needs, family commitments and lifestyle. It also does not start until 65 at the earliest.
So most people pair CPF LIFE with another source of income: other investments, part-time work or rental income. For Han, that other source is rental income from US property. Relying on salary and savings alone carries its own risk, which is explained in why the "Safe Singapore Script" is risking your wealth. Any retirement plan should be checked against your own situation, ideally with a qualified financial adviser.
Summary: What is CPF LIFE?
CPF LIFE is Singapore's national annuity. It turns your CPF Retirement Account into a monthly income from 65 for life, and the amount depends on your retirement sum, your plan and when you start. It is a strong foundation for retirement, and for most people it works best alongside another source of income.
Source: rules and figures in this guide are from the CPF Board's official website (cpf.gov.sg), as of November 2026.